Key takeaways:
- The Nasdaq fell 5.5% Thursday, then opened 1.23% higher Friday.
- Investors raised concerns that a Democrat-controlled Congress could tighten oversight of AI and data-centre construction.
- US employers added 165,000 jobs in October, according to the BBC, while unemployment fell to 4.1%.
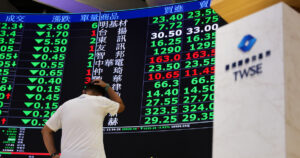
US technology shares rebounded Friday after an AI-led sell-off wiped more than $3.2 trillion from the value of the US stock market the previous day, according to The Guardian. The recovery followed steep losses that spread from Wall Street to Asian and European markets.
The tech-heavy Nasdaq Composite opened 1.23% higher Friday and continued to climb in early trading, recovering part of its 5.5% drop on Thursday. The S&P 500, which had fallen 4.4% Thursday, also opened slightly higher and gained. The Dow Jones Industrial Average opened a little lower before holding roughly flat, the BBC reported.
Companies tied closely to artificial intelligence took some of the sharpest losses Thursday. Nvidia shed hundreds of billions of dollars in market value as its shares fell more than 9%, then rose more than 6% at the start of Friday trading. Chipmakers AMD and Micron each lost more than 17% Thursday; by Friday, AMD was up about 12% and Micron more than 8%. SpaceX shares rose more than 7% Friday and Tesla gained nearly 3% after both fell sharply Thursday, according to the BBC.
Investors have linked the rout in part to the Democrats’ sweeping US midterm election victory. The party won control of both houses of Congress and key contests in states involved in the race to build AI data centres. A number of Democrats campaigned for new rules governing AI and data centres, raising concerns among investors that tighter oversight could slow development.
Russ Shaw, founder of Tech London Advocates, told the BBC that the election result signalled a need for AI companies to rethink how they deal with the public. “The incoming Congress is going to really focus on AI in a very dramatic way,” he said. Companies building data centres in communities where residents face rising energy costs “have to be better neighbours,” he added.
Ben Barringer, head of technology research at Quilter Cheviot, cautioned against assuming the election would stop construction. “It is too easy to say that the Democrats will be bad for datacentres,” he told The Guardian. He expected delays in approvals but said officials could seek to allocate resources more fairly.
The sell-off also revived concerns about whether enormous spending on AI will pay off. The Guardian reported that one valuation measure, the cyclically adjusted price-to-earnings ratio, had reached its highest level since 2000. It also noted that seven major technology companies — Nvidia, Apple, Google, Microsoft, Meta, Amazon and Tesla — make up more than a third of the S&P 500, tying index-tracking funds closely to their performance.
A stronger-than-expected US jobs report added another factor for traders to weigh Friday. The BBC reported that employers added 165,000 jobs in October, more than twice the number analysts expected, while unemployment eased to 4.1% from 4.2% in September. Professional and business services added 70,000 jobs, and healthcare added 42,000.
Neil Birrell, chief investment officer at Premier Miton, said the figures suggested the US economy was “running hard” and that the risks troubling markets might pose less of a threat to the broader economy than feared. Mark Haefele, chief investment officer at UBS Global Wealth Management, told The Guardian that despite the latest “market indigestion,” he did not think fundamentals justified a prolonged downturn.

Be First to Comment